Categories
Buying a Home, Market UpdatesPublished November 13, 2026
Before You Panic About Rates, Read This
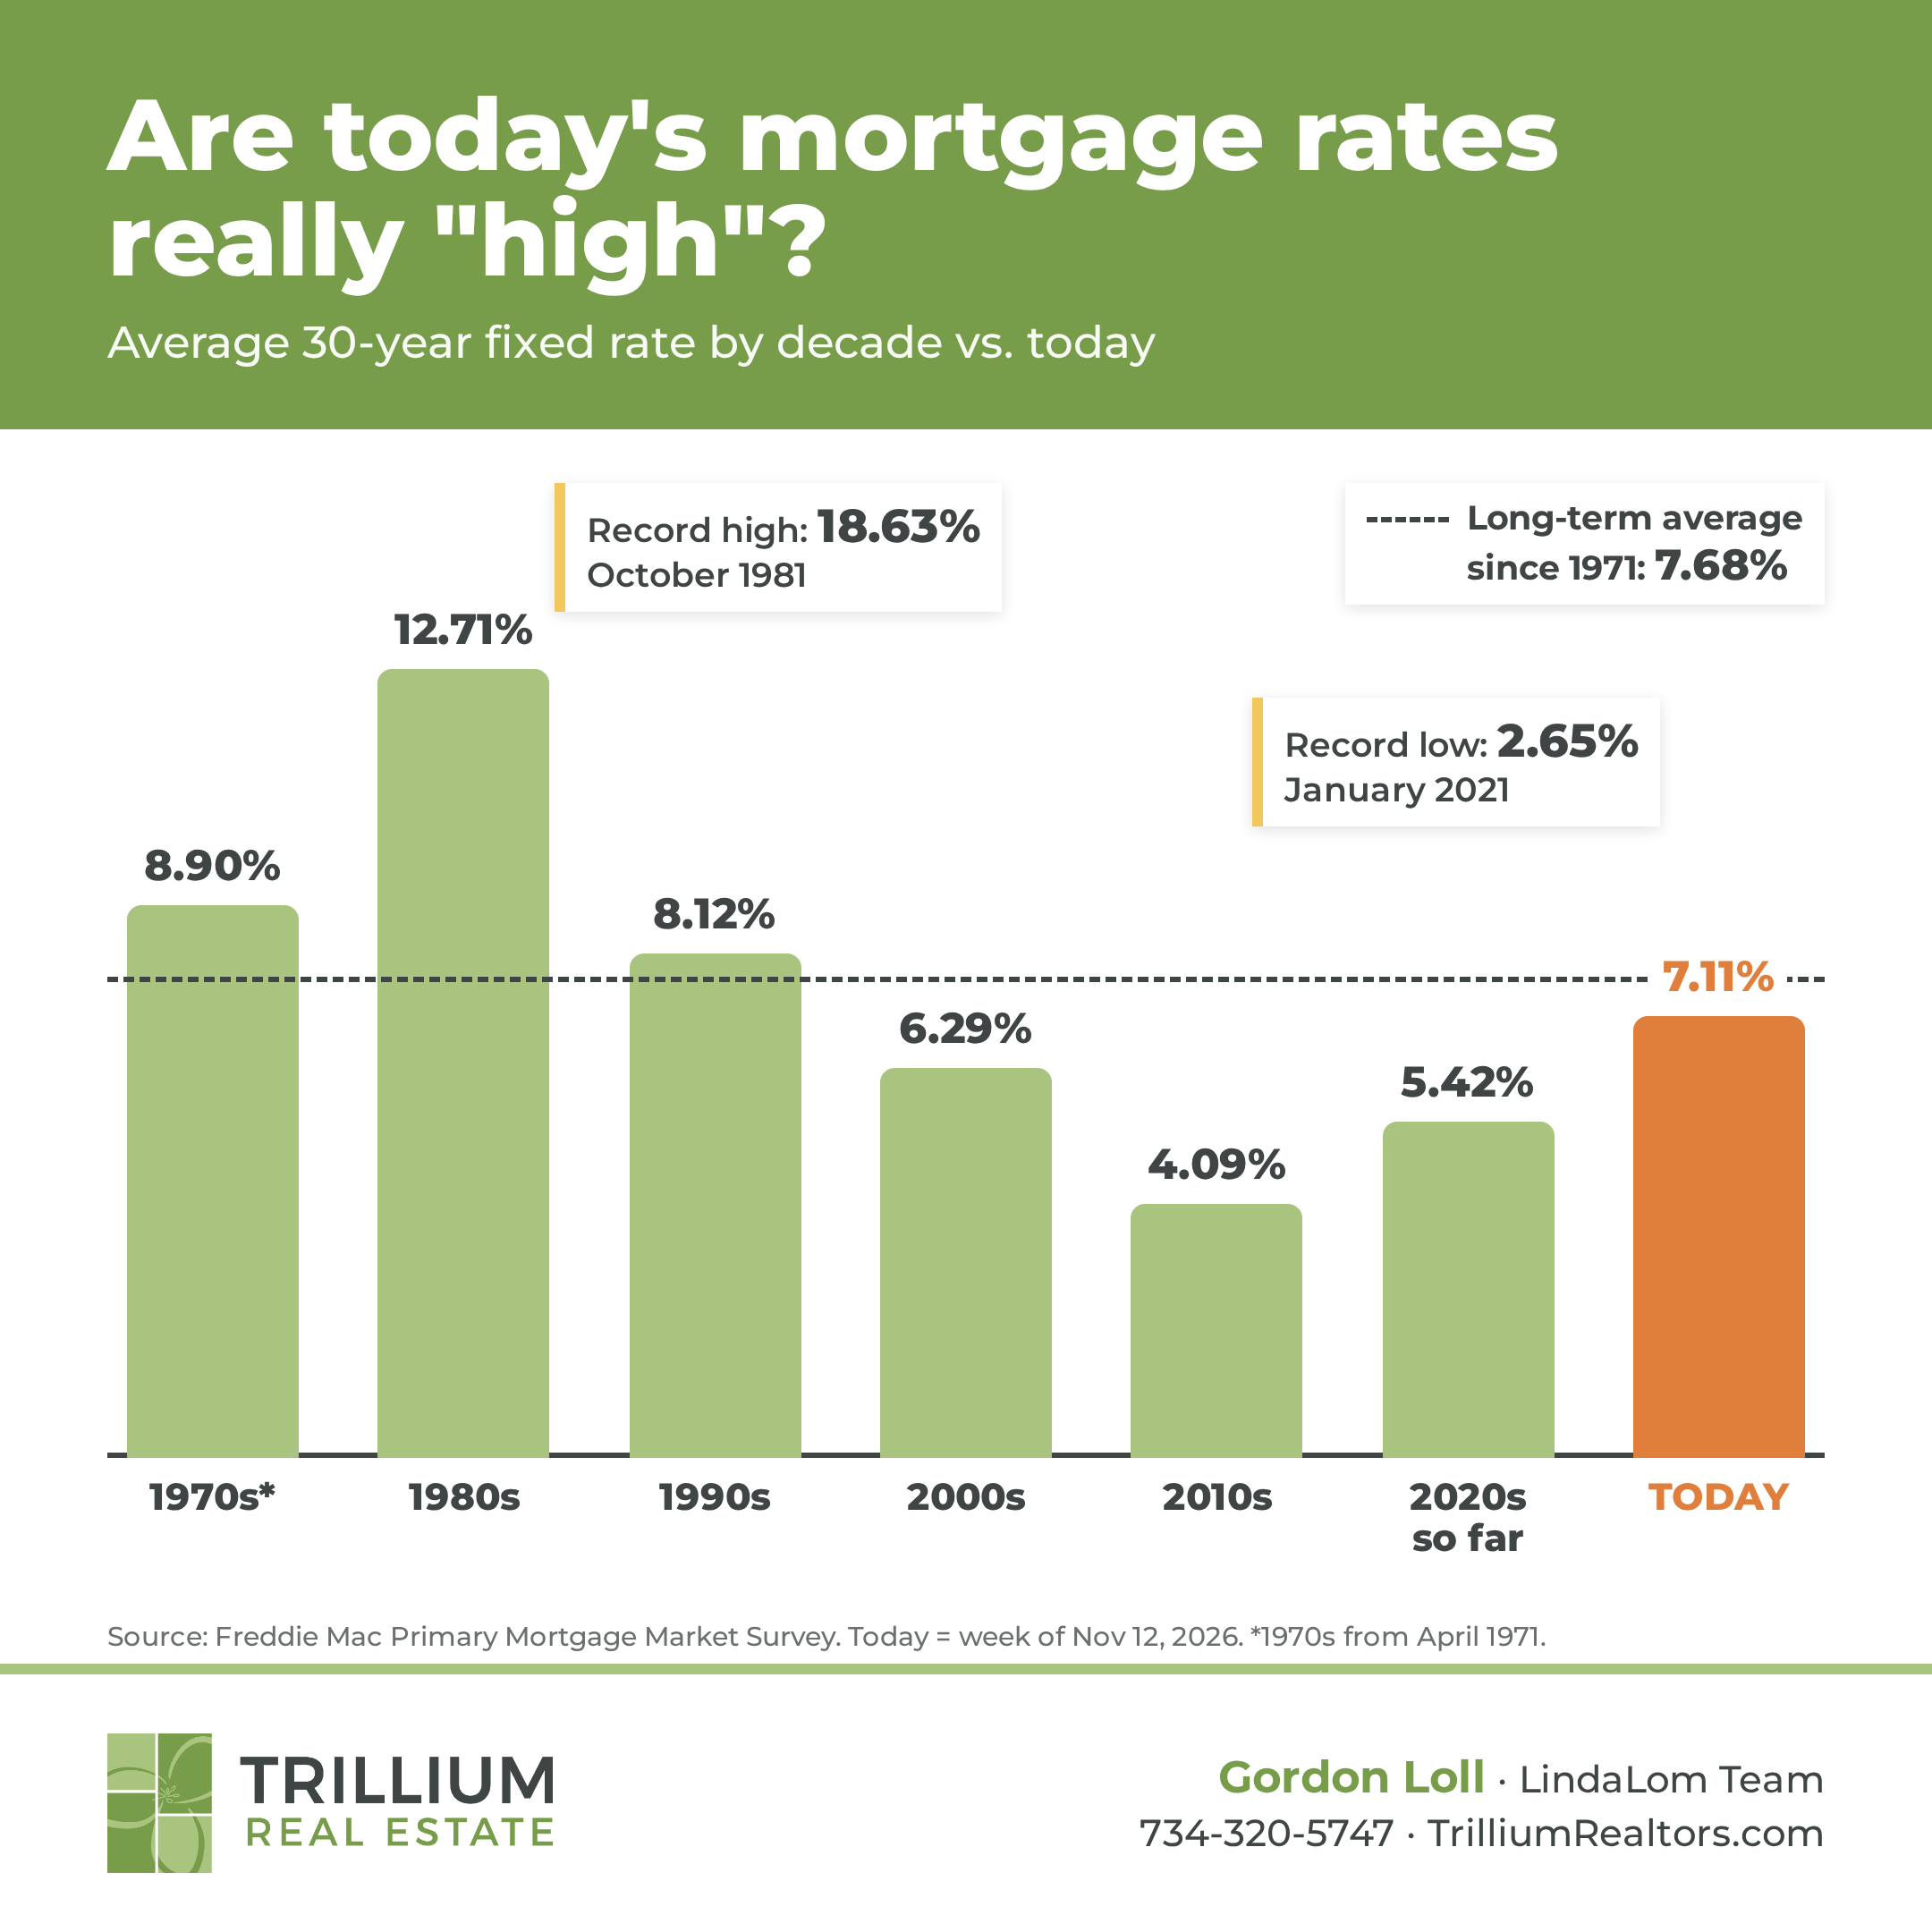
This week the average 30-year fixed mortgage rate is 7.11%, according to Freddie Mac. That's down a little from 7.18% last week. It still feels high if you remember the 3% rates of 2021. But compared with the last 55 years, today's rate looks very different.
Mortgage rates by decade
Here is the average 30-year fixed rate in each decade, compared with today:
| Period | Average 30-year fixed rate |
| 1970s (from April 1971) | 8.90% |
| 1980s | 12.71% |
| 1990s | 8.12% |
| 2000s | 6.29% |
| 2010s | 4.09% |
| 2020s so far | 5.42% |
| Today (week of Nov. 12, 2026) | 7.11% |
| Long-term average since 1971 | 7.68% |
The record high was 18.63% in October 1981. The record low was 2.65% in January 2021.
Today's rate is actually below the long-term average. The super-low rates of 2020 and 2021 were the exception, not the norm.
But history doesn't make your monthly payment any easier
Let's be honest about that. A year ago the average rate was 6.24%. On a $400,000 loan, today's rate adds about $231 a month to the principal and interest payment ($2,691 vs. $2,460). That's more than $2,700 a year.
For many buyers, that means a smaller budget, a longer search, or rethinking the home they had in mind. If that's you, we understand, and you're not alone.
There's often more room to work with than you think
- A good local lender can walk you through loan programs and down-payment options.
- Rate buydowns can lower your payment, especially in the first years of the loan.
- Sometimes sellers are willing to help with closing costs.
- Buyers have more homes to choose from than they did a few years ago.
Our job is to help you find a home that fits your life and your budget.
Why waiting for lower rates can cost you
When rates go down, buyers who have been waiting come back into the market all at once. More buyers means more competition, more multiple offers, and higher prices. Waiting for a lower rate can mean paying a higher price for the home.
You can refinance later if rates fall. You can't go back and change the price you paid.
Let's look at your numbers
Thinking about buying in Ann Arbor or the surrounding area? Let's sit down, look at real numbers for your situation, and make a plan, with no pressure. We can also connect you with excellent local lenders. Call or text Gordon Loll of the LindaLom Team at 734-320-5747, or email Gordon@TrilliumRealtors.com.
Sources: Freddie Mac Primary Mortgage Market Survey, week of Nov. 12, 2026; decade and long-term averages calculated from weekly Freddie Mac data since April 1971. Payment example is principal and interest only on a 30-year fixed loan and does not include taxes or insurance. This is general information, not a loan offer; talk with a lender about your situation. Equal Housing Opportunity.
Sandi Smith
President & Broker | Sandi Smith | Trillium Real Estate
or another way